
Housing Market Trends and Predictions
The housing market never stands still. Interest rates, government policy, local jobs and shifting buyer habits all push prices and inventory around, often in different directions at once. If you plan to buy, sell or invest, you need a clear read on these forces before you sign anything. This guide looks at the housing market trends and predictions that took shape in 2025: where the market stood, what changed, and what those shifts mean for your next move.
Key Takeaways: Housing Market Trends
- Housing market trends are driven by rates, inventory and jobs.
- Buyers should compare total monthly costs, not just price.
- Sellers benefit from realistic pricing.
Table of Contents
Introduction
The year 2025 brought plenty of change. Mortgage rates moved up and down, and buyers started asking for different things from their homes. Policy shifts, such as broad tariffs on imports, added another layer by pushing up the cost of some building materials. Below, we walk through these housing market trends and predictions one by one, so you can see which ones matter for your situation and which are just background noise.
1. Current State of the Housing Market
a. Mortgage Rates and Affordability
As of April 2025, the average 30-year fixed mortgage rate stood at approximately 6.64%. That was a slight dip from earlier in the year, which gave some buyers a little breathing room. Affordability was still the main problem, though, because home prices kept climbing, just at a slower pace than before.
A simple habit helps here: run your numbers at the rate you’re quoted and again at a rate about one point higher. If the higher payment still fits, a small rate bump won’t derail your plans. Many lenders also like to see your total monthly debt, including the new mortgage, stay at or below roughly 36% to 43% of your gross income.
b. Home Prices and Inventory Levels
The national average home value was about $357,138 at the time, a 2.6% rise over the previous year. That’s a clear cooldown from the rapid jumps of the pandemic years. Inventory stayed tight in many areas, though, and a short supply of homes keeps prices firm even when demand softens.
2. Impact of Economic Policies
a. Tariffs and Construction Costs
The 10% tariff on all imports affected housing in two ways. First, imported materials, appliances and fixtures got more expensive, which raised building costs and can push up new home prices. Second, the economic uncertainty around the tariffs made mortgage rates jumpy. At times that worked in buyers’ favor, with short windows of lower rates.
b. Regional Market Shifts
Some regions, especially in the southern United States, turned into buyer-friendly markets. Cities like Miami and Jacksonville saw more homes for sale and longer days on market. That gives buyers more room to negotiate on price, ask for repairs or request help with closing costs.
3. Emerging Trends in Home Design
a. Floor Plan Innovations
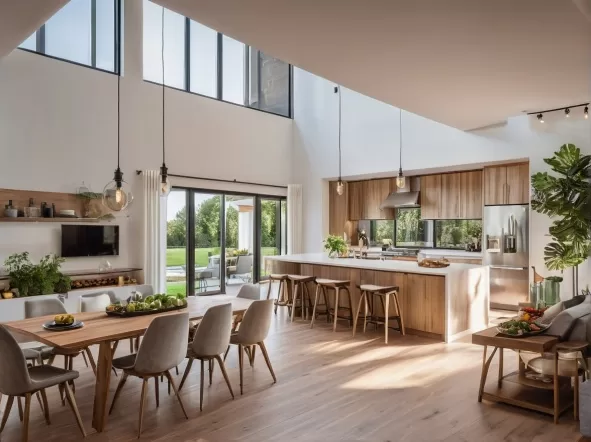
Modern home designs keep moving toward open, airy floor plans that can adapt as your needs change. One example is the New American House Plan, a 2,025 sq ft layout that joins the living, dining and kitchen areas into one connected space. If you like this style, check the sight lines from the kitchen, think about where sound will travel and make sure there’s still a door you can close for work calls.
b. Sustainable and Smart Homes
Demand for energy-efficient homes keeps growing. Solar panels, smart thermostats, good insulation and durable, low-maintenance materials are now on many buyers’ wish lists. If you’re selling, gather utility bills and receipts for any efficiency upgrades, since buyers like proof. If you’re buying, ask about the age of the roof, windows and HVAC system, because those big-ticket items affect your monthly costs as much as the price does.
4. Price Predictions and Outlook
a. Home Price Trajectory
Experts expected modest price growth through 2025. In the UK, for example, the lender Nationwide forecast growth of 2% to 4%, depending on interest rates and the wider economy. Treat national forecasts like these as a rough guide only. Prices on your street can move quite differently from the average, so local sales data matters more for your decision.
b. Mortgage Rate Fluctuations
Mortgage rates offered some relief, but the market still reacts quickly to economic data and policy news. If you’re shopping for a home, get pre-approved, know your maximum monthly payment and be ready to lock a rate when it fits your budget. Ask your lender how long a rate lock lasts and what an extension would cost.
c. Regional Variations
Different metro areas can move in opposite directions. Places with growing tech employers or big new infrastructure projects may see faster price gains. Areas where jobs are leaving can see prices stall or slip. Before you buy, look at local job news, new construction permits and how long homes in your target neighborhood are sitting on the market.
5. Strategies for Buyers and Sellers
a. For Buyers
- Financial Preparedness: Get your finances in order, with a strong credit score and as large a down payment as you can manage, to qualify for better mortgage terms.
- Market Research: Stay updated on local market conditions, as trends can vary significantly by region.
- Flexibility: Be open to exploring different neighborhoods or property types to find better deals.
b. For Sellers
- Competitive Pricing: Set a realistic price based on current market analyses to attract serious buyers.
- Home Staging: Fix small, visible flaws and stage key rooms so the home shows and photographs well.
- Timing: Consider market seasonality and local demand to time your listing effectively.
Mortgage payment calculator
Estimate your monthly payment and the true cost of the loan.
Conclusion
Today’s housing market brings both challenges and openings. Economic policy, regional differences and changing buyer tastes all shape what you’ll face, so stay alert and flexible. Buyers and sellers who keep informed and plan ahead tend to make better calls. Watch rates and local sales data over the coming months, and revisit your plan whenever conditions shift.
What Buyers and Sellers Should Watch
Mortgage rates, local inventory and job growth drive most housing markets. When rates fall, demand usually rises quickly, while limited supply keeps prices firm in many regions.
Buyers should compare total monthly costs, not just price, and get pre-approved early. Sellers benefit from pricing realistically and fixing visible issues before listing.
Check what you can afford at today’s rates with the mortgage affordability calculator.
Frequently Asked Questions
Will house prices go down?
It depends on the local market. Areas with high inventory and slowing job growth may see price cuts, while places with limited supply often stay stable or rise.
Is now a good time to buy a home?
The right time depends on your finances and plans. If you can afford the monthly cost comfortably and plan to stay several years, waiting for perfect market timing is rarely necessary.
Related Guides
